Choosing Your Beneficiaries
Last Updated: 12/11/2026 16:54The beneficiary section inside your Pension App account makes it easy to choose who receives your death benefits.
Our interface makes it simple to customise your legacy in real time:
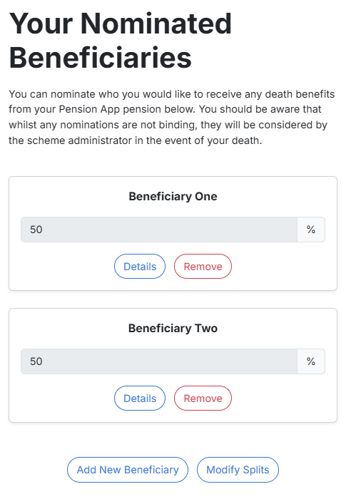
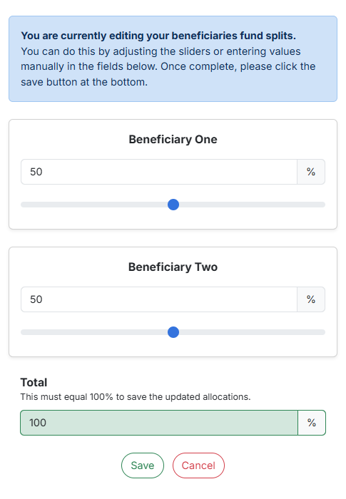
Interactive Allocation Sliders: You can instantly adjust your fund splits using smooth sliding toggles or manual percentage boxes.
Instant Validation: Our system calculates your totals automatically. It ensures your allocations hit exactly 100% before allowing you to lock them in.
Complete Record Freedom: You can effortlessly view beneficiary details, remove old allocations, or add new loved ones with a single click.
Log into your Pension App account today to review and confirm your current allocations.
Why Setting Your Beneficiaries Matters
Many savers assume that a standard will automatically cover their pension pot. In reality, pension funds generally do not form part of your legal estate. Instead, the pension scheme administrators hold ultimate legal discretion over who receives your money.
By logging in and setting your beneficiaries, you provide clear guidance to our administrators. Please be aware that whilst any nominations you make are not binding, they will be thoroughly considered by the scheme administrator in the event of your death. Taking five minutes to update this expression of wish gives your family invaluable peace of mind.
The Tax Advantages
Passing on a pension is often highly tax-efficient. Under current rules, if you pass away before the age of 75, your beneficiaries can usually inherit the fund free of Income Tax. If you pass away after age 75, beneficiaries will normally pay Income Tax on withdrawals at their marginal rate.
Important Estate Note: Please keep in mind that under the Finance Act 2026, the law is changing. For deaths on or after 6 April 2027, most unused pension funds and pension death benefits will be brought within the value of a person's estate for Inheritance Tax (IHT) purposes.
Important Information
A pension is a long-term investment not normally accessible until age 55 (57 from 6 April 2028 unless the plan has a protected pension age). The value of your investments (and any income from them) can go down as well as up, which would have an impact on the level of pension benefits available.
Your pension income could also be affected by the interest rates at the time you take your benefits. The tax implications of pension withdrawals will be based on your individual circumstances, tax legislation and regulation, which are subject to change.